Setting Financial Goals and Managing Student Debt

Before investing a single dollar, taking time to determine what you are saving for provides crucial direction for your investment strategy. Do you want to make a major purchase when you graduate, create a safety net, or start saving for retirement? Once you have a goal in mind, that becomes the starting point for choosing appropriate investments. Consider both short-term and long-term financial goals and evaluate how much risk you are willing to take given your timeline and circumstances.
For students carrying student loans, a general rule is to check whether the student loan interest rate is lower than the average expected return on investment. If your loans carry high interest rates, prioritizing debt repayment may make more mathematical sense than investing. However, if loans carry relatively low interest rates, contributing to investments—particularly tax-advantaged accounts like a Roth IRA—while making minimum loan payments can work in your favor over time. The decision requires honest assessment of your personal financial situation.
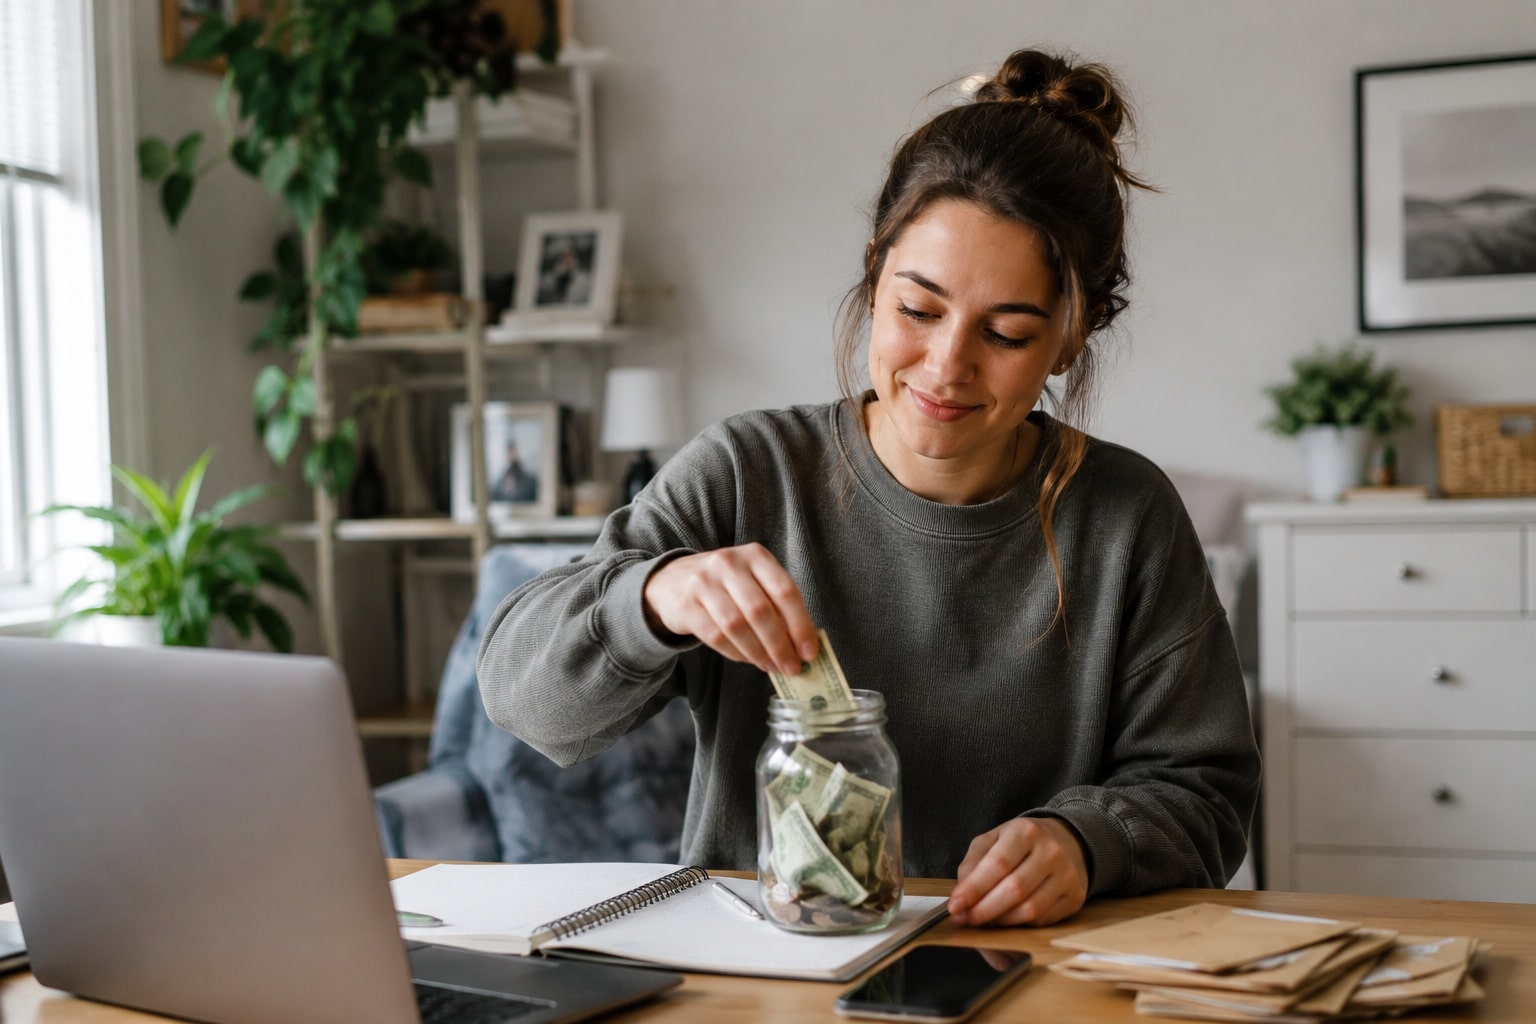
Creating a budget that includes regular investment contributions—even small ones—establishes the discipline that separates successful long-term investors from those who never get started. Automating savings can help students stick to a budget and retain money for consistent investments. That daily coffee purchase or weekly food delivery might seem insignificant, but redirecting that spending toward investments means that years from now, those small amounts can turn into meaningful savings through the power of compound growth.
Understanding Investment Fees
Pay attention to how much money you spend on trading commissions and platform fees. A one percent annual fee reduces your final balance by roughly twenty-five percent over thirty years. The general recommendation is to aim to pay no more than about two percent of the value of your trade in commissions. Most modern platforms offer commission-free trading, making this easier than ever for students to avoid fee erosion.
Learning Investment Fundamentals While in School
Prior to investing any money, getting the basics down first provides a foundation for all future financial decisions. Start by learning common investment terms and concepts. What are stocks and bonds? What about mutual funds, dividends, and portfolios? These fundamentals might seem basic, but understanding them thoroughly prevents costly mistakes later. Many students find success by taking a finance course at their college or utilizing free online educational sources such as Investopedia, Khan Academy, or reputable investment channels that teach rather than promote speculation.
Many brokerage platforms now include educational tools designed specifically for beginning investors. Fidelity and similar firms offer resources that teach investing concepts, financial planning, and responsible risk-taking alongside their trading platforms. These integrated educational features allow students to learn while doing—studying investment concepts and then immediately applying them with real money in small amounts. This practical education often proves more valuable than theoretical knowledge alone.
Understanding your risk tolerance before diving into investing is crucial. As a college student with decades until retirement, you can generally afford to take on more risk than older investors—but only risk you can emotionally and financially handle. Some students discover they lose sleep when their portfolio drops even slightly, indicating they may need a more conservative approach regardless of their time horizon. Self-awareness about how you respond to market volatility helps build a sustainable long-term investment strategy.
Your Path to Financial Independence Starts Now
The greatest advantage a college student possesses isn’t found in any particular stock pick or investment strategy—it’s the decades of compounding time that lies ahead. Whether you begin with five dollars or five hundred, the act of starting matters far more than the initial amount. Modern technology has removed nearly every barrier that once prevented young people from participating in wealth-building activities reserved for those with substantial capital. By establishing sound financial habits now, educating yourself about investment fundamentals, and contributing consistently to well-diversified portfolios, you position yourself to benefit from one of the most powerful forces in finance: time. The student who begins investing today, even modestly, will almost certainly outpace the person who waits for the perfect moment or the perfect amount—because that perfect moment is always now, and the perfect amount is whatever you can sustainably contribute.