How to Start Investing as a College Student With Little Money
Building wealth begins with small steps—and college is the perfect time to start your investment journey.
The notion that you need thousands of dollars to begin building wealth is one of the most persistent financial myths holding young people back. The reality is that learning how to start investing as a college student with little money has never been more accessible. With commission-free trading platforms, fractional shares, and accounts that require no minimum deposit, students can begin their investment journey with amounts as modest as a single dollar. The advantage of starting early cannot be overstated—compound interest rewards those who begin young, turning even small, consistent contributions into substantial sums over decades. College students possess something that money cannot buy: time. By understanding the basics of investing and leveraging modern financial technology, students can establish habits and portfolios that serve them for the rest of their lives.
Build an Emergency Fund Before You Invest
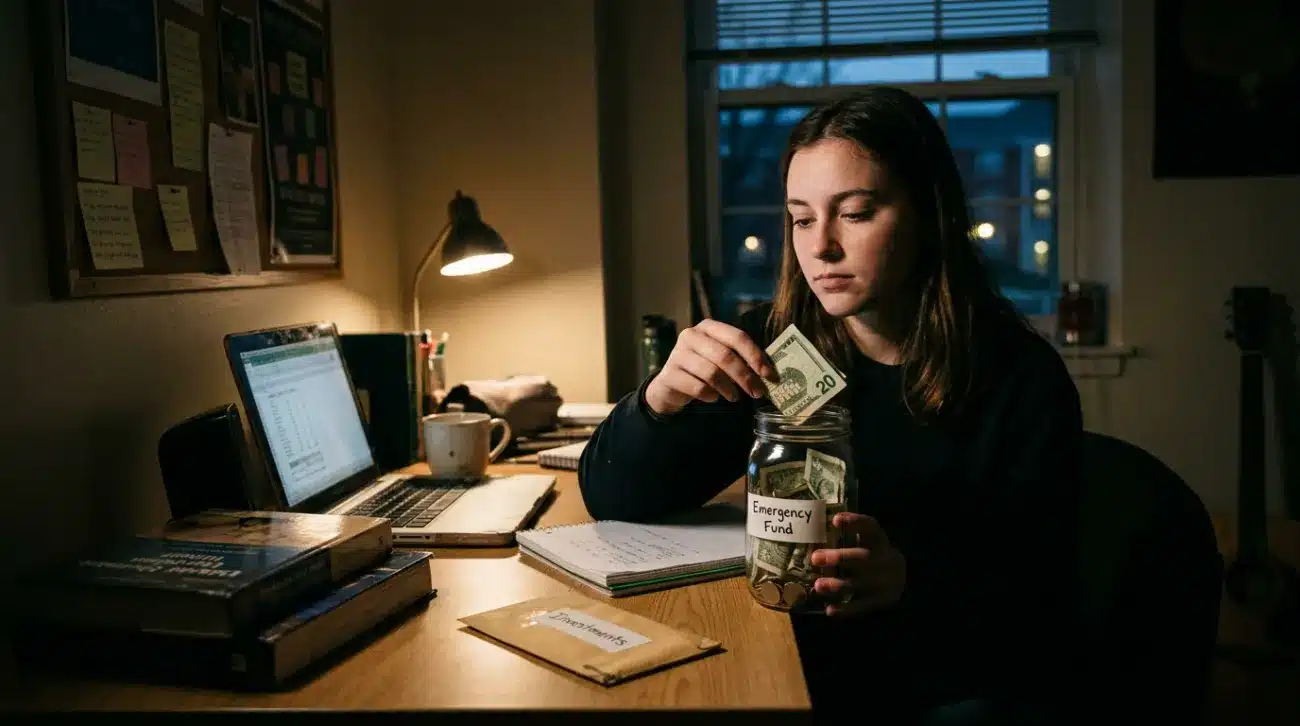
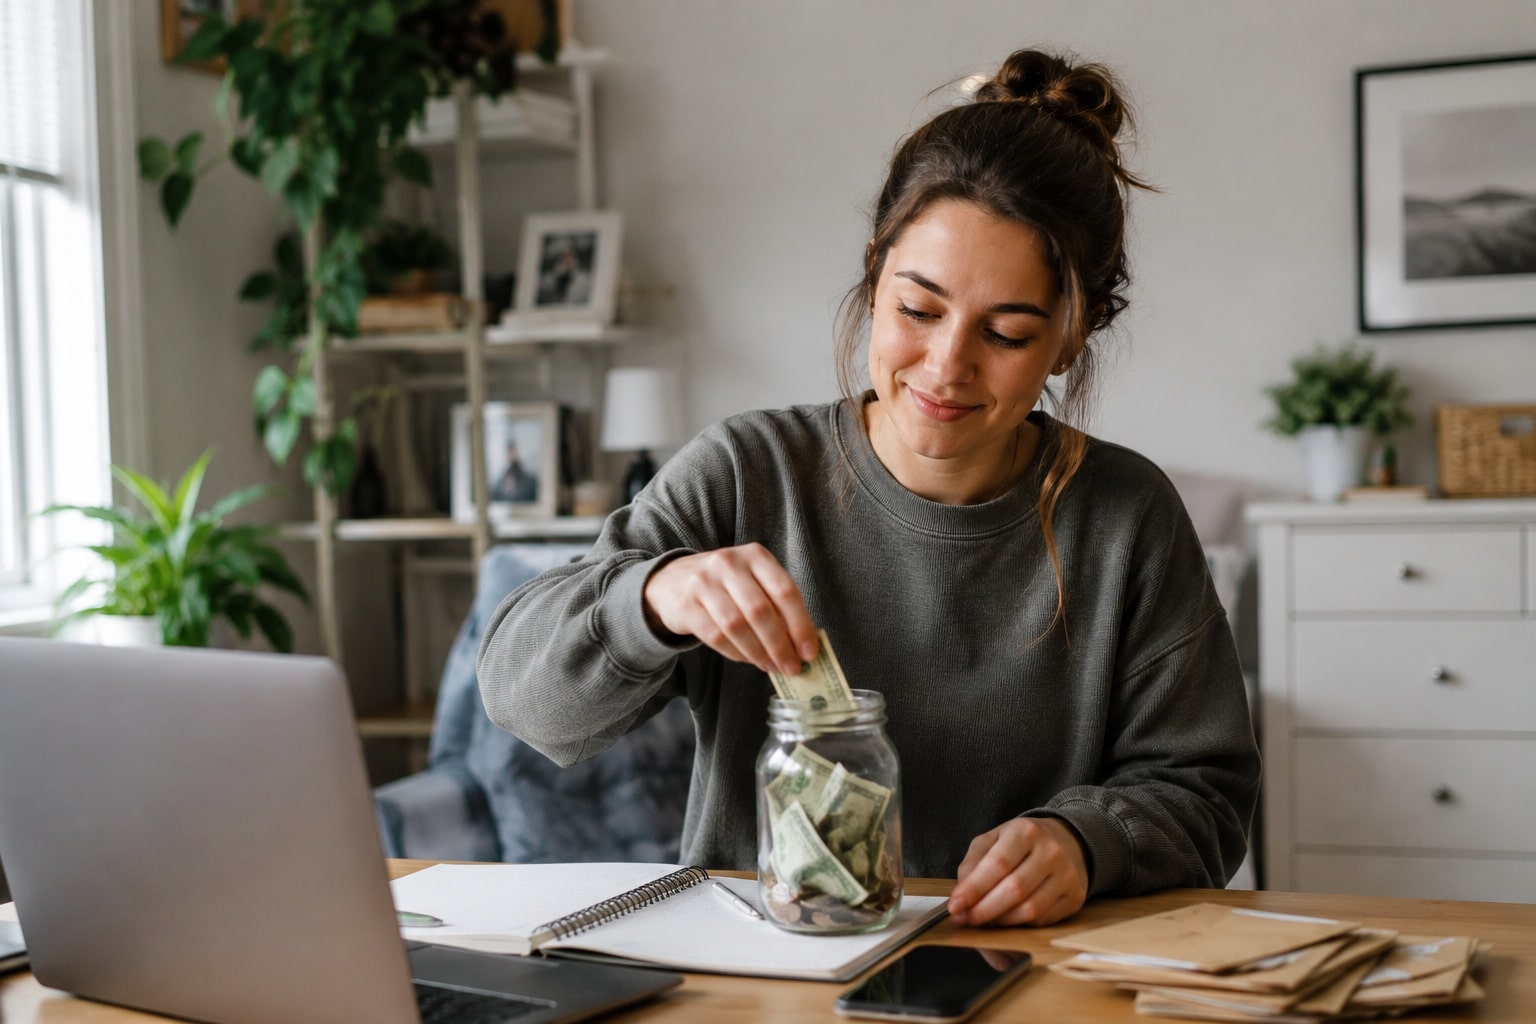
Before directing any money toward investments, financial experts consistently recommend establishing a baseline of financial stability. This means creating an emergency fund that can cover unexpected expenses without derailing your financial progress. A general recommendation is to have an emergency fund that can cover daily necessities for three to six months. For college students, this target may be more modest—even having a few hundred dollars set aside can prevent the need to sell investments at an inopportune time or take on high-interest debt when unexpected costs arise.
High-yield savings accounts have become an essential tool for this purpose. These accounts typically offer much higher interest rates than standard checking accounts, providing a risk-free way to earn extra returns on cash needed for emergencies. In 2026, high-yield savings accounts are offering rates around four to five percent APY, making them a solid foundation before moving into market-based investments. The key is keeping this money liquid and accessible while still earning competitive returns.
Key Financial Milestone
Students don’t need thousands or even hundreds of dollars to start investing. Setting aside just ten or twenty dollars each week can be enough to begin building a portfolio while developing crucial financial habits.
Commission-Free Investment Apps for Student Budgets

The democratization of investing has transformed what’s possible for students with limited funds. Modern brokerage platforms have eliminated many traditional barriers to entry, making it feasible to invest with minimal capital. The best investing apps for college students offer zero account minimums, fractional shares, built-in education, and clear paths to long-term wealth creation. These platforms make it easy to get started with just a few dollars while teaching core investing principles along the way.
Robinhood has made commission-free stock trading mainstream and remains one of the most popular investing apps with Gen Z and college students. The platform allows users to buy stocks, ETFs, options, and cryptocurrency with no commissions, and fractional shares start at just one dollar. This means you can own a piece of expensive stocks like Amazon or Apple without needing to purchase a full share. Similarly, platforms like Fidelity offer access to full-service brokerage features with no commissions and no account minimums, alongside tools that teach budgeting, saving, and goal-setting.
For students who prefer a more automated approach, micro-investing apps like Acorns use the concept of spare change to help build investments automatically. Acorns also offers an IRA option called Acorns Later, allowing users to have both regular and retirement investing on the same platform. The fee for investing starts at just three dollars per month, though students should be mindful of how fees impact smaller account balances.
Robinhood
Zero account minimum, zero commissions on stocks and ETFs, fractional shares from one dollar. Best for beginners seeking a simple mobile-first experience.
Fidelity
No minimum to open accounts, no maintenance fees, fractional share investing available. Offers IRAs with no minimum deposits and commission-free trading.
Acorns
Automated round-up investing starting at five dollars. Subscription-based pricing from three to twelve dollars monthly. Includes retirement account options.
Webull
Zero deposit minimums with commission-free stocks, ETFs, and options. Offers powerful research tools and fractional shares starting at one dollar.
Index Funds and ETFs for Beginner Investors

For students just beginning their investment journey, index funds and exchange-traded funds represent some of the most sensible starting points. Index funds are based on major market indices like the Standard and Poor’s 500, allowing students to invest in a ready-made portfolio of stocks without having to choose individual companies themselves. This approach provides instant diversification—spreading risk across hundreds of companies rather than concentrating it in a single stock.
The importance of diversification cannot be overstated for new investors. Spreading investments across different asset classes means that if one investment performs poorly, others might perform well and mitigate the effects on the overall portfolio. Exchange-traded funds typically offer this diversification at low cost, making them particularly attractive for students working with limited capital. Rather than trying to pick winning stocks—a strategy that even professional money managers often fail at—students can capture the overall growth of the market through broad-based index funds.
The strategy of dollar-cost averaging pairs especially well with index fund investing. This approach involves investing small amounts regularly regardless of market conditions, which helps smooth out the impact of market volatility over time. For a college student, this might mean investing twenty or fifty dollars every paycheck into a total market index fund, building a substantial portfolio over the course of their college years and beyond.
Opening a Roth IRA While Young
The thought of opening an individual retirement account before your twentieth birthday may seem extreme, but it represents one of the smartest financial decisions a young person can make. Roth IRAs in particular offer an excellent investment strategy for young people because contributions are made with after-tax dollars, meaning all qualified withdrawals in retirement will be completely tax-free. For someone in their late teens or early twenties, decades of tax-free growth can result in significantly more wealth than taxable investment accounts.
For the 2026 tax year, the Roth IRA contribution limit is seven thousand five hundred dollars for individuals under age fifty. However, you can only contribute up to the amount of earned income you have for the year. A student working part-time who earns three thousand dollars can contribute up to three thousand dollars to a Roth IRA. There are no age requirements for contributing to a Roth IRA, so individuals of any age with qualifying income can contribute. Single filers must have a modified adjusted gross income of less than one hundred fifty-three thousand dollars to make a full contribution, a threshold most college students will easily fall under.
Many of the same platforms that offer taxable brokerage accounts also provide Roth IRA options. Fidelity IRAs have no minimum to open and no account maintenance fees, meaning a student could deposit just five dollars and begin investing commission-free. The key is establishing the account and building the habit of contributing regularly, even if the amounts are small initially.
The Power of Starting Early: $100 Monthly Investment Growth
Avoiding Trendy Stocks and Emotional Decisions
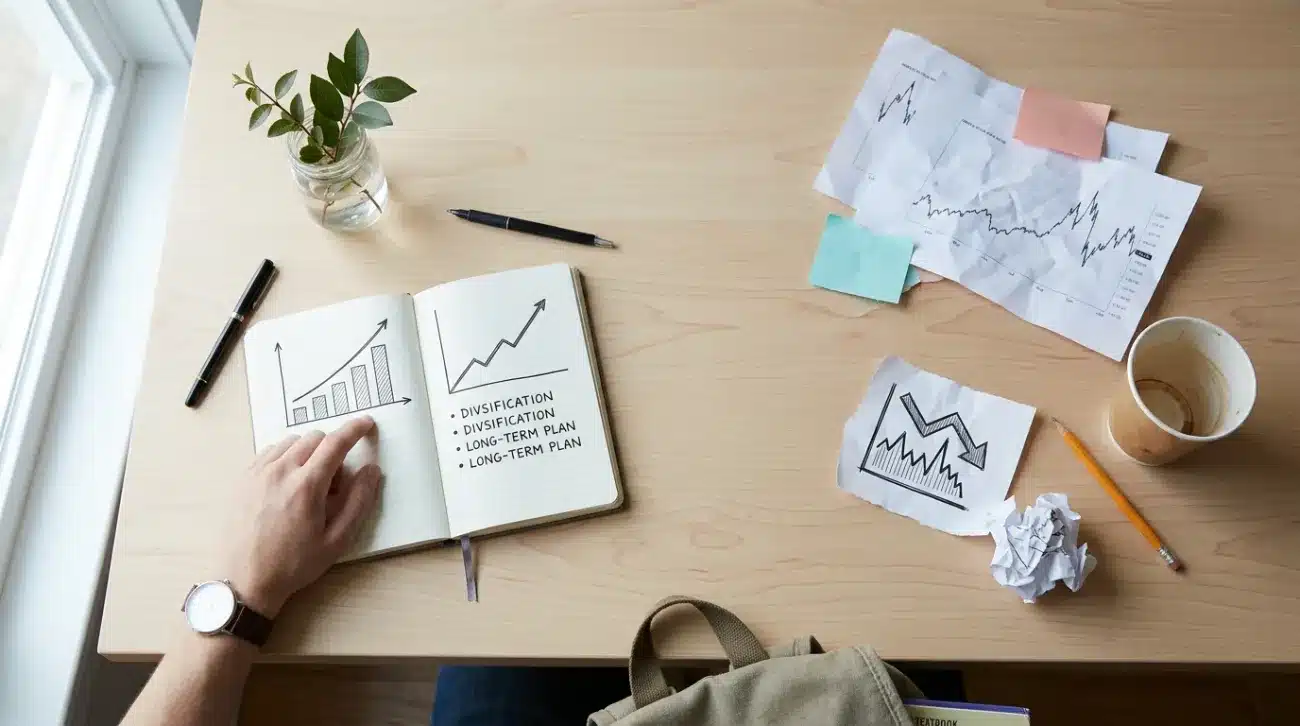
The meteoric rise and popularity of trendy stocks and cryptocurrencies should be seen as a warning to young investors rather than an opportunity to chase quick gains. The GameStop saga of recent years illustrated this danger clearly—as the stock rose to unprecedented prices, thousands of people bought at extremely elevated levels thinking the climb would continue. Unfortunately, many of those investors wound up losing tremendous amounts of money when reality set in. When you’re young, it is best to choose investments that are well-respected with a lengthy history to help evaluate performance.
Understanding concepts like market cycles, valuation, and investor psychology enables you to make informed decisions rather than chase trends. Maintaining a long-term perspective and avoiding emotional investing can help navigate market fluctuations that are inevitable over any investment timeline. The goal for a college student isn’t to get rich overnight—it’s to learn and become more self-assured so you can be a smart investor for the next few decades. Linking investing to the rest of your financial life, such as budgeting and student loan management, will prevent common mistakes that derail long-term wealth building.
Social media and internet personalities promising overnight success should be viewed with extreme skepticism. Instead of following hot tips, focus on sustainable, long-term strategies like dollar-cost averaging, where you invest small amounts regularly regardless of market conditions. If you do decide to invest in new opportunities or individual stocks, never bet all of your hard-earned money on any single investment.
Key Takeaway
College students get one special benefit that money cannot buy: time. You can experiment with different investment approaches and learn without needing to show immediate results. The habits and knowledge developed now will compound alongside your investments for decades to come.